
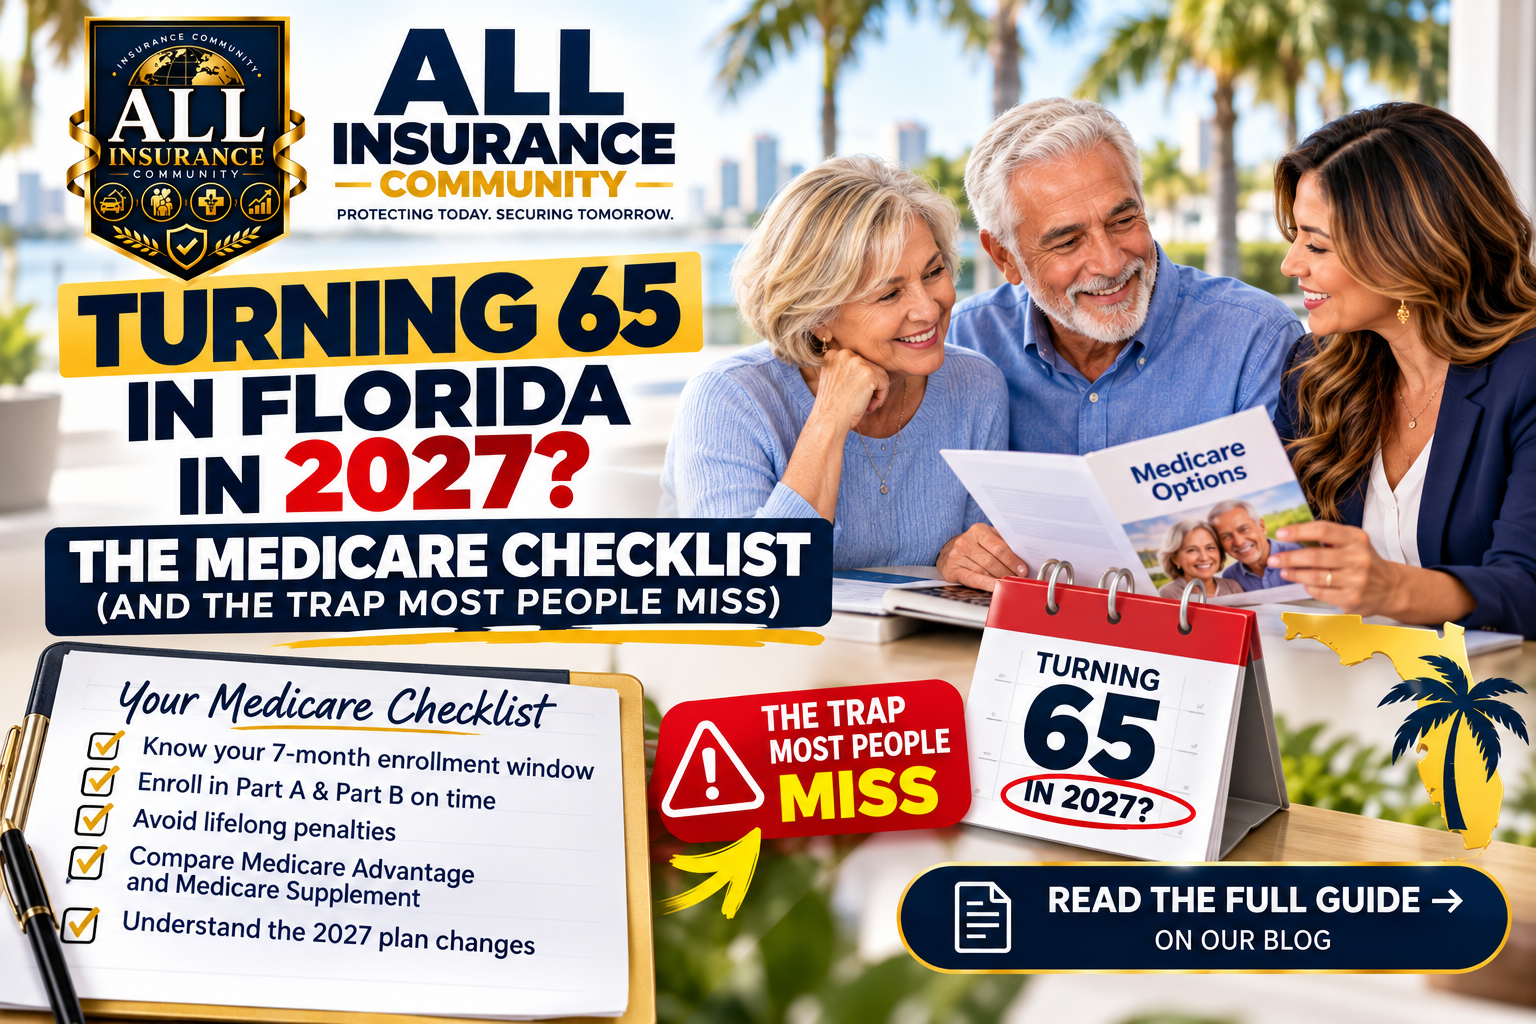
Turning 65 in Florida in 2027? The Medicare Checklist (and the Trap Most People Miss)
Turning 65 in Florida in 2027? The Medicare Checklist (and the Trap Most People Miss)
Turning 65 is one of the biggest financial decisions of your life — and in 2027, it comes with a twist most guides won’t tell you about. Yes, you need the usual checklist: enroll on time, avoid penalties, pick a plan. But this year, with major insurers cutting Medicare Advantage plans across Florida, the choice you make at 65 could quietly lock you out of options later. This is the honest, complete guide — the checklist and the trap most people walk into.
First, the timeline you can’t miss
Your Initial Enrollment Period (IEP) is a 7-month window centered on your 65th birthday: the 3 months before, your birthday month, and the 3 months after. This is your penalty-free window to enroll in Medicare Part A and Part B.
Miss it, and the penalties are not small — and they’re not temporary. The Part B late penalty is permanent, adding 10% for each 12-month period you could have had it. The Part D drug penalty is also lifelong. These follow you for the rest of your life, so the single most important rule at 65 is: don’t miss your window.
One tip most people don’t know: if your birthday falls on the 1st of the month, Medicare treats you as turning 65 the month before — your whole window shifts one month earlier.
The Turning 65 checklist (in order)
Here’s what actually needs to happen, step by step:
- Create your my Social Security account at ssa.gov so you can enroll and track your status.
- Decide about Part A and Part B. Most people take both at 65. If you’re still working with employer coverage (20+ employees), you may be able to delay Part B without penalty — but confirm this first, because getting it wrong is costly.
- Watch your HSA. If you contribute to a Health Savings Account, enrolling in Medicare changes what you can contribute. Ask HR before you enroll.
- Enroll in Part A and B through Social Security — online, by phone, or at a local office.
- Choose your coverage path (this is the big one — see below).
- Add Part D drug coverage if your path doesn’t include it, to avoid the lifelong penalty.
- Keep every letter and confirmation number. You may need them later to prove your rights.
The decision that matters most: Advantage or Supplement?
At 65, your biggest choice is between two paths:
- Medicare Advantage — a private plan that bundles everything, often with a $0 premium, but with networks, copays, and referrals.
- Original Medicare + a Medicare Supplement (Medigap) + Part D — a monthly premium, but see any doctor nationwide who takes Medicare, with predictable costs and no networks.
Most people are drawn to the $0 premium of Advantage. That’s exactly where the 2027 trap is hiding.
The trap most people miss (and why 2027 makes it worse)
Here’s what almost no other guide will tell you plainly.
When you turn 65 and enroll in Part B, you get a one-time, six-month Medigap Open Enrollment window. During it, you can buy any Medicare Supplement plan in Florida with no health questions — guaranteed. This window comes once, and it never comes back the same way.
If you choose Medicare Advantage at 65 and later decide you want a Medigap plan — because your plan cut benefits, left the market, or you got sick of the network — Florida generally requires medical underwriting to switch. That means the insurer can review your health and turn you down or charge you more. If you’ve developed any condition, that door may be closed.
Now add the 2027 reality: major insurers are dropping and shrinking Medicare Advantage plans across Florida. Hundreds of thousands of members are getting non-renewal letters this fall. People who picked Advantage years ago — while healthy — are now trying to move to a Supplement and discovering they may not qualify. Some get a special guaranteed-issue window when their plan terminates; many don’t get the full choice they’d have had at 65.
The lesson isn’t “always pick Supplement.” It’s this: the choice you make at 65 has consequences years down the road, and 2027 is proving it in real time. Getting it right the first time — with your health, your budget, your doctors, and your future in mind — is worth far more than chasing a $0 premium today. If you’re weighing the two, our Medicare Advantage vs. Medigap in Florida guide breaks it down, and our Plan G vs Plan N in Florida guide covers the two most popular Supplement plans.
The mistakes that cost Florida retirees the most
- Missing the Part B window → permanent penalty.
- Assuming $0 premium means $0 cost → Advantage copays add up fast if you get sick.
- Not checking your doctors and drugs → the “cheapest” plan may not cover them.
- Waiting until the last minute → rushed decisions in your birthday month lead to regret.
- Not knowing your one-time Medigap window → the single most expensive mistake of all.
Why work with a local, independent agent
At 65, the stakes are high and the rules are easy to get wrong. As an independent, bilingual agency, we’re not tied to one company — we compare Medicare Advantage, Medigap, and Part D across multiple carriers, run a full doctor-and-medication check, and explain your options in plain language, in English or Español. We’ll tell you honestly which path fits your situation — including the long-term consequences most people don’t hear about until it’s too late.
You can also confirm official rules and dates at Medicare.gov.
Turning 65 soon? Let’s get it right the first time
You only get one Initial Enrollment Period, and in Florida, one clean shot at a Supplement without health questions. Don’t guess, and don’t let a $0-premium pitch cost you your future options. Let’s review your doctors, your medications, and your plans together — free, no pressure, no obligation.
📞 Call us: (561) 633-6208
📅 Schedule a free appointment (no obligation, no pressure): https://calendly.com/allinsurancecommunity/15min
🗣️ English or Español · Boynton Beach, FL